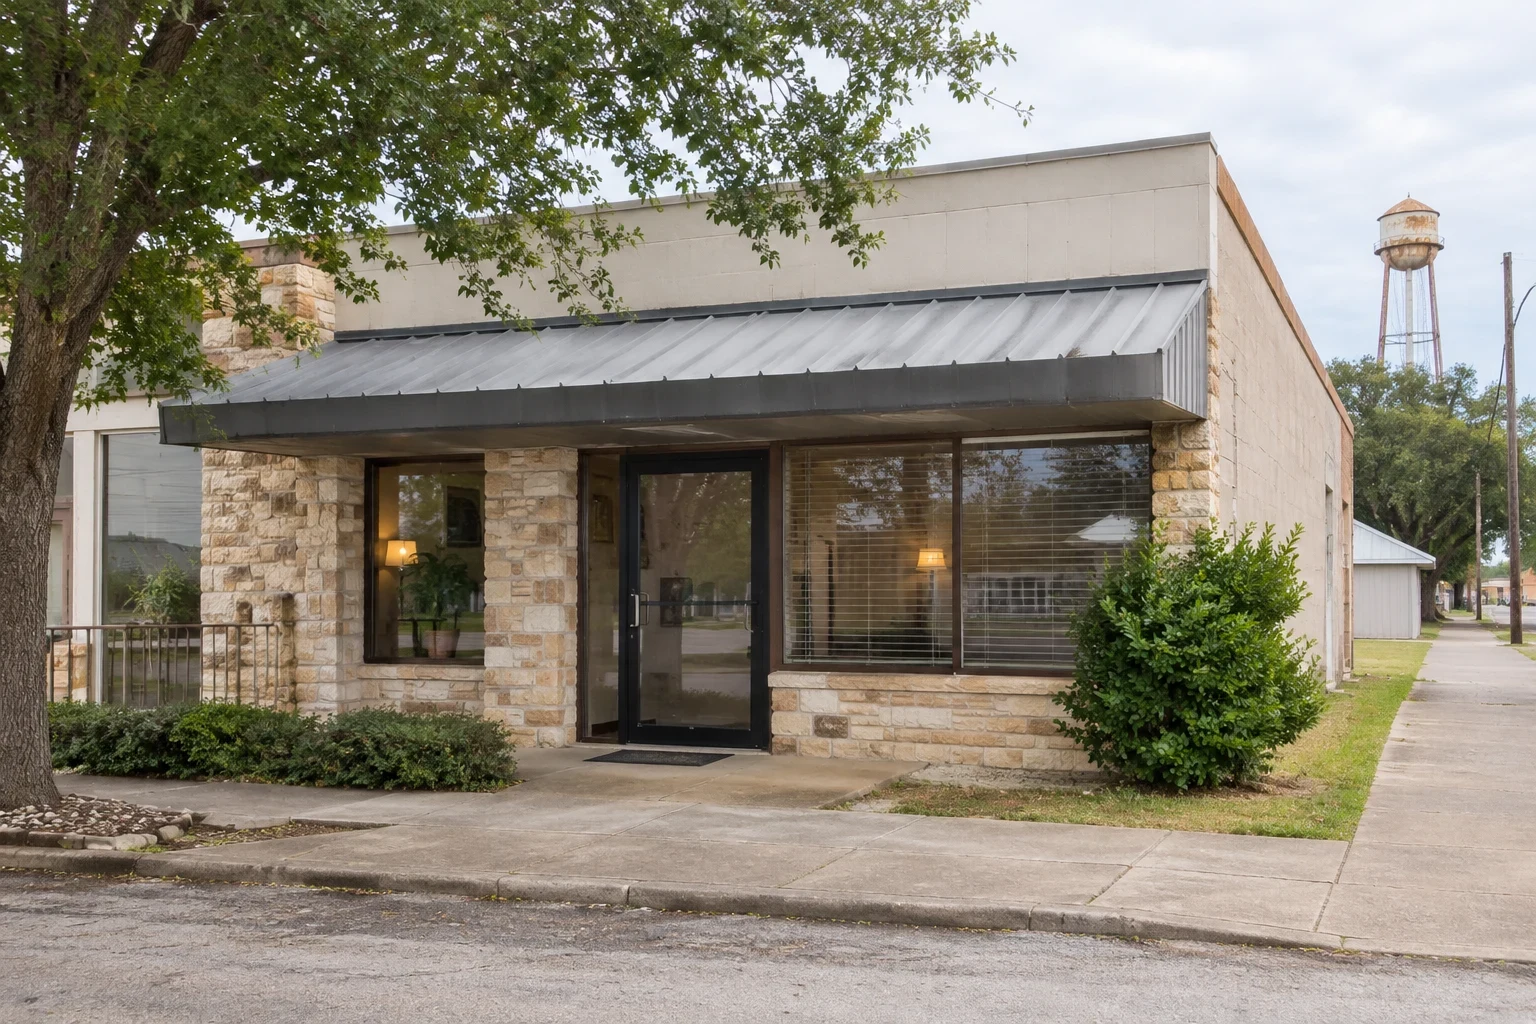
Home Loans in Smithville and the Towns Around It
We write purchase, refinance and equity loans for borrowers in Smithville and across the surrounding counties. Before we suggest a loan, we review your credit, income, assets and the property itself, then tell you plainly which programs fit and which ones will stall at underwriting.
Where We Lend
Most of our borrowers live or buy in Smithville, Bastrop, Elgin, Cedar Creek and Camp Swift, along with smaller communities such as Circle D-KC Estates and Wyldwood. We also work with buyers headed east toward La Grange, Giddings and Schulenburg. You can meet a loan officer at our office or work with us by phone and video, so distance rarely slows a file down.
The location of a property changes more than the address on the note. It can decide whether a USDA loan is available, whether the lender will require flood insurance, and how the appraiser values land against the structure. We check those points early, before you pay for an appraisal or sign a contract, so the loan you start is the one that reaches closing.
Towns we cover from Smithville
- Smithville
- Bastrop
- Circle D-KC Estates
- Camp Swift
- La Grange
- Wyldwood
- Giddings
- Cedar Creek
- Elgin
- Schulenburg
Not on the list? Call (512) 881-6278 and ask.
What Shapes a Loan Around Here
- Rural eligibility
- Much of the open country outside the larger towns may fall inside USDA-eligible areas, which can allow purchase with no down payment for buyers under the income limits. Eligibility runs by exact address, not by town name, so we look up the specific property before recommending the program.
- Acreage, wells and septic
- Plenty of properties here sit on a few acres with a private well and a septic system. Appraisers weigh land value against the house, and FHA, VA and USDA appraisals may call for a water test or a septic inspection. Manufactured houses need a permanent foundation and must be titled as real property to qualify for most programs.
- Floodplain and insurance
- Parts of the area lie near the Colorado River and its creeks. If a property falls in a FEMA special flood hazard zone, the lender requires flood insurance, and that premium counts in your monthly payment and debt-to-income ratio. We pull the flood determination early so the number is in your budget from the start.
- Texas equity rules
- Texas limits home equity loans and HELOCs to 80 percent combined loan-to-value on a primary residence and sets a waiting period between application and closing. We measure your available equity against that cap before you apply, so you know the realistic line amount up front.
Start With a Look at Your File
Tell us about the property and your income, and a loan officer will walk through what the review shows. From there we can take your loan application, run a pre-qualification or quote current rates.